
Dakota Peters
Inspections Officer
When it comes to investing in property, identifying and assessing risks is a critical step in making informed decisions and safeguarding your investment. Understanding potential risks allows you to take appropriate measures to mitigate, avoid, or accept them based on their severity and likelihood. This article will guide you through the process of identifying and assessing risks in property investments and provide insights on how to take action through risk mitigation, avoidance, or acceptance.
Detection – The first step in assessing risk in a property is to first detect risks that are likely to occur these may include the likelihood of a natural disaster in an area, the likelihood that a tenant is to default or vandalise a property, or the likelihood that a property will be worth less in in value in the future. Detecting risk can be done through careful research and analysis of available data historical trends and through leveraging the experience of professionals in the industry.
Severity – once you’ve detected all the potential risks in an investment property the next step is to understand the severity of that risk in the event that it was to become a reality. This is essentially understanding what the worst-case scenario is if this risk were to become reality. You can understand this through careful research and analysis of previous occurrences in other scenarios and understanding the financial and non-financial cost of that particular scenario. For example, in the event that a natural disaster such as a flood or fire were to occur, and your investment property would be damaged to the point of complete this repair what would be the cost of a total rebuild of that property.
Likelihood – the last step in identifying risk is to calculate as best you can the likelihood of that potential risk occurring. This can be done again through careful research and analysis of each of the risks that you’ve identified and that way you can understand whether you would like to mitigate, avoid or accept the risk of this particular outcome occurring. For example, if a particular area has a history of flood or bushfire that has a high severity but a 1 in 100-year likelihood then you may choose to either insure against this risk or accept the risk occurring depending on your risk appetite.
Mitigating, Avoiding & Accepting Risk – Now that you fully identified each of the risks this severity and likelihood, you can begin to take action on each of these risks by either mitigating, avoiding or accepting each of the risks.
Identifying and assessing risks in property investments is a crucial aspect of successful investing. By carefully detecting potential risks, understanding their severity and likelihood, and taking appropriate action, investors can navigate the complex landscape of property investment with greater confidence. Whether it’s through risk mitigation, avoidance, or acceptance, investors can tailor their strategies to align with their risk appetite and investment goals.
Remember that risk management is an ongoing process that requires continuous monitoring and adaptation as market conditions evolve. Stay informed, leverage available data and expert advice, and always evaluate the potential risks against the potential rewards. With a comprehensive understanding of risks and a proactive approach, you can make well-informed decisions and increase the likelihood of achieving favourable outcomes in your property investment journey.
Ultimately, each investor’s risk tolerance and investment objectives will determine the appropriate approach to managing risks in property investments. Always seek professional advice and conduct thorough research to make informed decisions tailored to your specific circumstances. By adopting a thoughtful and proactive approach to risk assessment, you can set yourself up for success and maximize the potential returns on your property investments.
Making Informed Financial Choices
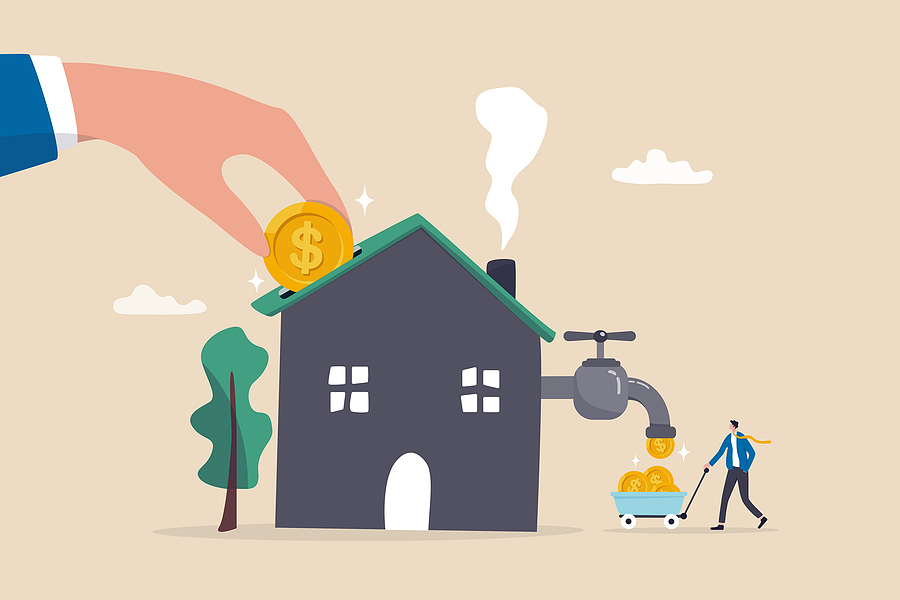
Negative gearing is a common investment strategy that involves borrowing money to invest in income-generating assets, such as real estate. While negative gearing can offer financial benefits, it’s essential to weigh the pros and cons before diving into this investment approach. In this article, we will explore the advantages and disadvantages of negative gearing investment property to help you make informed financial decisions.
One of the primary advantages of negative gearing is the potential for tax benefits. When the costs of owning and maintaining an investment property exceed the rental income it generates, the resulting loss can be offset against other taxable income. This can reduce your overall tax liability and potentially increase your cash flow.
Negative gearing allows investors to leverage borrowed funds to acquire properties that have the potential for long-term capital growth. In markets where property values appreciate over time, the investor may benefit from the increase in property value, which can lead to substantial returns on investment in the future.
Investing in negatively geared properties can help you accumulate assets over time. While the rental income may not cover the property expenses initially, as the property appreciates in value and rental income increases, the investor can build equity and create a portfolio of income-producing properties.
Including negatively geared properties in your investment portfolio can provide diversification benefits. Real estate investments have the potential to perform differently from other asset classes such as stocks or bonds. By spreading your investments across different asset types, you can reduce risk and achieve a more balanced portfolio.
Cons of Negative Gearing Investment Property: (h2)
The primary drawback of negative gearing is the potential cash flow strain. If the rental income falls short of covering the property expenses, you will need to cover the shortfall out of your own pocket. This can put significant pressure on your finances, particularly if unexpected expenses arise or interest rates increase.
Real estate markets can experience fluctuations in property values and rental demand. While negative gearing can provide tax benefits, it also exposes investors to the risks associated with market volatility. If property values decline or rental income decreases, the investor may face difficulties in meeting loan repayments and maintaining cash flow.
Negatively geared properties may not generate sufficient rental income to cover the ongoing expenses, resulting in a reliance on capital growth for a return on investment. This means that investors must carefully assess the potential for future rental income growth and balance it against the costs of holding the property.
Government policies and regulations surrounding negative gearing can change over time. Alterations to tax laws or restrictions on negative gearing benefits may impact the profitability of your investment. Staying informed about potential policy changes and adapting your investment strategy accordingly is crucial.
Negative gearing investment property can be a viable strategy for some investors, but it’s important to carefully evaluate its pros and cons. Consider your financial situation, risk tolerance, and long-term investment goals. It’s advisable to consult with financial advisors or property professionals who can provide personalized guidance based on your circumstances. By thoroughly assessing the advantages and disadvantages, you can make an informed decision about whether negative gearing is the right investment approach for you.
Important Disclaimer: Consult an Accountant, Registered Tax Agent, or Financial Professional Before Considering Negative Gearing
Before embarking on any investment strategy, particularly negative gearing, it is crucial to seek personalized advice from qualified professionals such as accountants, registered tax agents, or financial advisors. The information provided in this article serves as a general overview of the pros and cons of negative gearing investment property, but it should not be considered as financial, or investment advice tailored to your specific circumstances.
As Buyer’s agent, I am often asked about getting access to Off-Market Properties and the advantages and disadvantages of purchasing off-market properties.
Essentially, off-market properties are those that are not listed on the open market and are typically sold through private channels such as word-of-mouth, personal networks, or a private real estate databases.
There are pros and cons to buying an off-market property, and as a buyer’s agent, it is important to weigh these factors when advising clients.
One of the most significant advantages of buying an off-market property is that there is usually less competition from other buyers. Since these properties are not publicly listed, they may not receive the same level of interest as a property that is actively being marketed. This can give buyers more leverage during negotiations and increase their chances of securing a property at a lower price.
Off-market properties are often sold through personal connections or private networks, giving buyers access to exclusive properties that are not available on the open market. This can be particularly beneficial for buyers looking for unique or rare properties that are not commonly available.
Flexibility in negotiations
Because off-market properties are not actively being marketed, there is usually more flexibility in the negotiation process. Sellers may be more willing to consider lower offers or make concessions that they would not have otherwise considered. This can result in a better deal for the buyer.
One of the primary disadvantages of off-market properties is the seller’s reaction to an offer. Potential property sellers will often ‘test out’ market feedback without paying for marketing costs by listing a property off-market. Seller’s can react to market feedback in different ways, they can decide not to sell the property off-market, place the property on the market or they can decide not sell the property at all and wait for better market conditions.
Since off-market properties are not publicly listed, buyers may not have access to the same level of information as they would if the property was listed on the open market. This can make it more challenging to assess the property’s condition, market value, and any potential issues that need to be addressed.
When purchasing an off-market property, buyers may not have the same level of representation as they would if they were working with a buyer’s agent in a traditional real estate transaction. Buyers may need to rely on the seller’s agent or their own due diligence to ensure that all aspects of the sale are handled correctly.
In the end, off-market properties can offer buyers unique opportunities to purchase exclusive properties with less competition and more flexibility in negotiations. However, they also come with the potential drawbacks of Seller’s Remorse, limited exposure to the property, and potentially limited representation. As a buyer’s agent, it is important to evaluate the pros and cons of off-market properties with clients to determine the best approach for their specific needs and goals.
QUEENSLAND’S property market is undergoing a secret boom as off-market property listings spike, according to Universal Buyers Agents.
Universal Buyers Agents property expert Darren Piper said 50% of his purchases are now off-market, as sellers look for new ways to sell their properties.
“We had a record quarter of property purchases recently and that has largely been driven by a large spike in the number of off market property sales,” Mr Piper said.
“A lot of vendors are starting to entertain the idea of an off market sale because they’re not ready to commit to advertising spend in what they see as an uncertain market.
“But while the number of official listings are still in short supply, the reality is that more than 30% of sales are now taking place off market through a network of buyers agents and vendors across all price points.”
Off-market listings are homes for sale which are not listed online and only shared with a real estate agent’s database of certified buyers.
“A lot of vendors have been asking what happens if we spend $5000 on marketing and we don’t sell?,” he said.
“During COVID-19 a lot of people were nervous about selling their home. Vendors are now testing the waters off-market off the back of this.
“But in the last three months we’ve seen the largest number of off market listings we’ve ever witnessed in our careers.”
“Through our network of agents we’ve been working hard to build up a database of these off market listings,” Mr Piper said. We usually have access to 250+ off market properties at any given time.
“Our buyers agents can then help them negotiate the sale, help them evaluate investment opportunities and navigate the ever-changing buying process.
Mr Piper said he expects the boom in off-market listings to continue to have momentum as sellers use it as a way to test the market before advertising it on traditional channels.
“A lot of vendors list off market before opening it up to a public sale four to six weeks later, it’s a way for them to test the waters,” he said.
“Queensland’s property market is very buoyant, with plenty of buying opportunities, we’re just doing things a little differently.”
To register for access to the off-market database visit universalbuyersagents.com.au
For media queries, photographs or interviews: Contact Darren on 0423 853 771

CONTROLLING your body language, being aware of auctioneer’s trickery and managing your bidding pace can help lead to success in auctions, says property expert Universal Buyers Agents.
UBA property expert Darren Piper said auctions can be an intimidating minefield for buyers and can lead to overpayment or disappointment if you fail to stick to a strategy.
“Buying your dream home in certain high demand areas may only be possible via an auction,” Mr Piper said.
“But it can often drive up the price by introducing competition and urgency to the buying process.
“Bidding at auctions is a skill you should spend some learning before you dive in or engage the help of a buyer’s agent to take control of the process for you.”
First and foremost, he recommends buyers start the bidding prepared as it does not follow the “offer and acceptance” method of a normal sale.
“The normal buying method allows you to do your research after the acceptance of your offer and before the signing of the property transaction contract,” Mr Piper said.
“This is not the case for an auction, you need to gather all the information you need before you enter the auction.
“You should also never run late for an auction; we’ve seen countless examples of buyers who arrived late only to find their preferred property had sold and even at prices well below their limit.
He recommends arriving early to register and position yourself smartly in the area, scan other bidders and determine their number.
Cooling off periods often don’t apply at auctions as well so buyers must be prepared to follow through on their bid at the fall of the hammer.
“You should always bid within an amount you can commit to,” Mr Piper said.
“That’s why you should always come to the auction knowing exactly what your budget is. A good trick is to set the maximum amount you can spend above a round number, if you decided that $900,000 is your upper limit, consider whether you could stretch to $904,000, this could help you win over bidders who have the same as your initial upper limit.”
Mr Piper also recommends controlling the bidding pace by slowing down and proceeding in smaller increments.
“Place your bid early on, as it allows you leeway to set the pace. You may also psychologically influence other bidders to continue in $5,000 increments, instead of $10,000, which is the average bidding increment at real estate auctions,” he said.
“You can also slow the pace by giving the auctioneers a hard time adding up the amounts before calling out the next bid, give your bids odd numbers that take a few more seconds to add up.”
Auctioneers also use several tricks including a keen eye for body language which can give a buyer’s intent away.
“Do your research beforehand, it makes it easier not to get caught up in emotion that can easily be read.”
Finally, he recommends if the process is too stressful or needs an expert eye, buyers should engage help from a buyer’s agent to ensure they get the best deal.
A Pre-Settlement inspection is performed 2-3 days before settlement. This allows the property sellers to amend any issues before settlement and avoid any delay.
This process is important to ensuring a smooth and stress-free handover!
We perform hundreds of Pre-Settlement inspections on behalf of our clients every year. It is rare that we come into issues with a property, BUT on the off chance that we do, it has saved our clients a world of pain and money in the long run.
Looking for a professional buyers agent to help you in making a simple and stress-free purchase?
Inspections Officer
Property Manager
Business Development Manager
Buyers Agent
Searcher and Sourcer
Searcher and Sourcer – Team Piper
Client Concierge
Associate
Buyers Agent
